What does home insurance cost in Massachusetts?
Short answer Modeled sample rates put a Massachusetts home at about $2,075 a year with a $500,000 dwelling limit, and a Springfield home closer to $2,530 — roughly 22% higher. Your own premium depends on rebuild cost, roof age, claims history, deductible and which carrier you land with.
Premiums here have been climbing. The Massachusetts Division of Insurance reported that average premiums rose again in 2024 across homeowners, condominium and tenant forms, and that Massachusetts residents bought about $3.9 billion in home insurance coverage that year — 12.7% more than 2023.
Encouragingly, the loss picture improved in the same period. Catastrophe losses fell to about $157 million across seven designated events, down sharply from the prior year, and the industry's adjusted combined ratio improved to 66.5% from 86.1%. That does not translate directly into lower premiums, but it is the kind of shift that makes carriers compete again — which is when shopping pays.
Sample rates by dwelling coverage
| Dwelling coverage | Sample annual rate | Per month |
|---|---|---|
| $300,000 | $1,325 | $110 |
| $400,000 | $1,645 | $137 |
| $500,000 | $2,075 | $173 |
| $600,000 | $2,445 | $204 |
| $700,000 | $2,825 | $235 |
How Massachusetts compares
| Location | Sample annual rate | Context |
|---|---|---|
| Springfield | $2,530 | About 22% above the statewide sample average |
| Worcester | $2,470 | Comparable urban rate |
| Boston | $2,395 | Lower than Springfield despite higher home values |
| Massachusetts (sample avg.) | $2,075 | $500k dwelling, no claims |
| National (sample avg.) | $3,005 | Massachusetts runs about 31% below |
These are modeled sample rates for illustration — not quotes, and not a prediction of your premium. Two homes on the same street can price very differently.
Want your actual number instead of an average?
The short version
- No Massachusetts law requires home insurance. Your mortgage lender does, and they can buy a policy for you and bill you if yours lapses.
- Water is the risk here, not fire. Non-flood water damage and freezing was the largest single cause of losses in 2024, and the average claim cost $16,639.
- Flood is never included. Not in a standard policy and not in the FAIR Plan. It is always a separate policy.
- If you heat with oil, you may be missing coverage you are entitled to buy. Massachusetts law requires carriers to offer oil leak coverage to homeowners with a certified system.
- Carrier spread is wide in Western Mass. Which is the whole argument for comparing instead of renewing on autopilot.
What does a homeowners policy actually cover?
Short answer A standard HO-3 policy has six parts: dwelling, other structures, personal property, loss of use, personal liability and medical payments. Most Massachusetts homes are written on this form. Knowing which part is thin on your policy is usually more useful than knowing your premium.
| Coverage | What it does | What to watch in Western Mass |
|---|---|---|
| Dwelling (Coverage A) | Rebuilds or repairs the structure itself after a covered loss — walls, roof, built-in systems. | Should reflect rebuild cost, not market value or your purchase price. Rebuild costs in Western Mass have moved a lot since 2020. |
| Other structures (Coverage B) | Detached garage, shed, fence, driveway. Usually a percentage of your dwelling limit. | A detached garage on an older Springfield lot can exceed the default 10% allowance. |
| Personal property (Coverage C) | Your belongings — furniture, clothing, electronics, appliances. | Jewelry, firearms and collectibles hit sub-limits fast. These often need a scheduled endorsement. |
| Loss of use (Coverage D) | Hotel, rent and extra food costs while your home is uninhabitable after a covered loss. | The limit matters more than people expect — a burst-pipe repair in January can take months. |
| Personal liability (Coverage E) | If someone is injured on your property or you damage someone else's property. | Default limits are often $100k–$300k. If your assets exceed that, an umbrella policy sits on top. |
| Medical payments (Coverage F) | Smaller medical bills for a guest hurt on your property, regardless of fault. | Low limit by design. It is there to settle minor incidents without a liability claim. |
If you want someone to read your current declarations page and tell you where the thin spots are, that is a free policy review — no obligation, and we will say so if your existing policy is already well built.
Interactive home coverage map
Home insurance at work
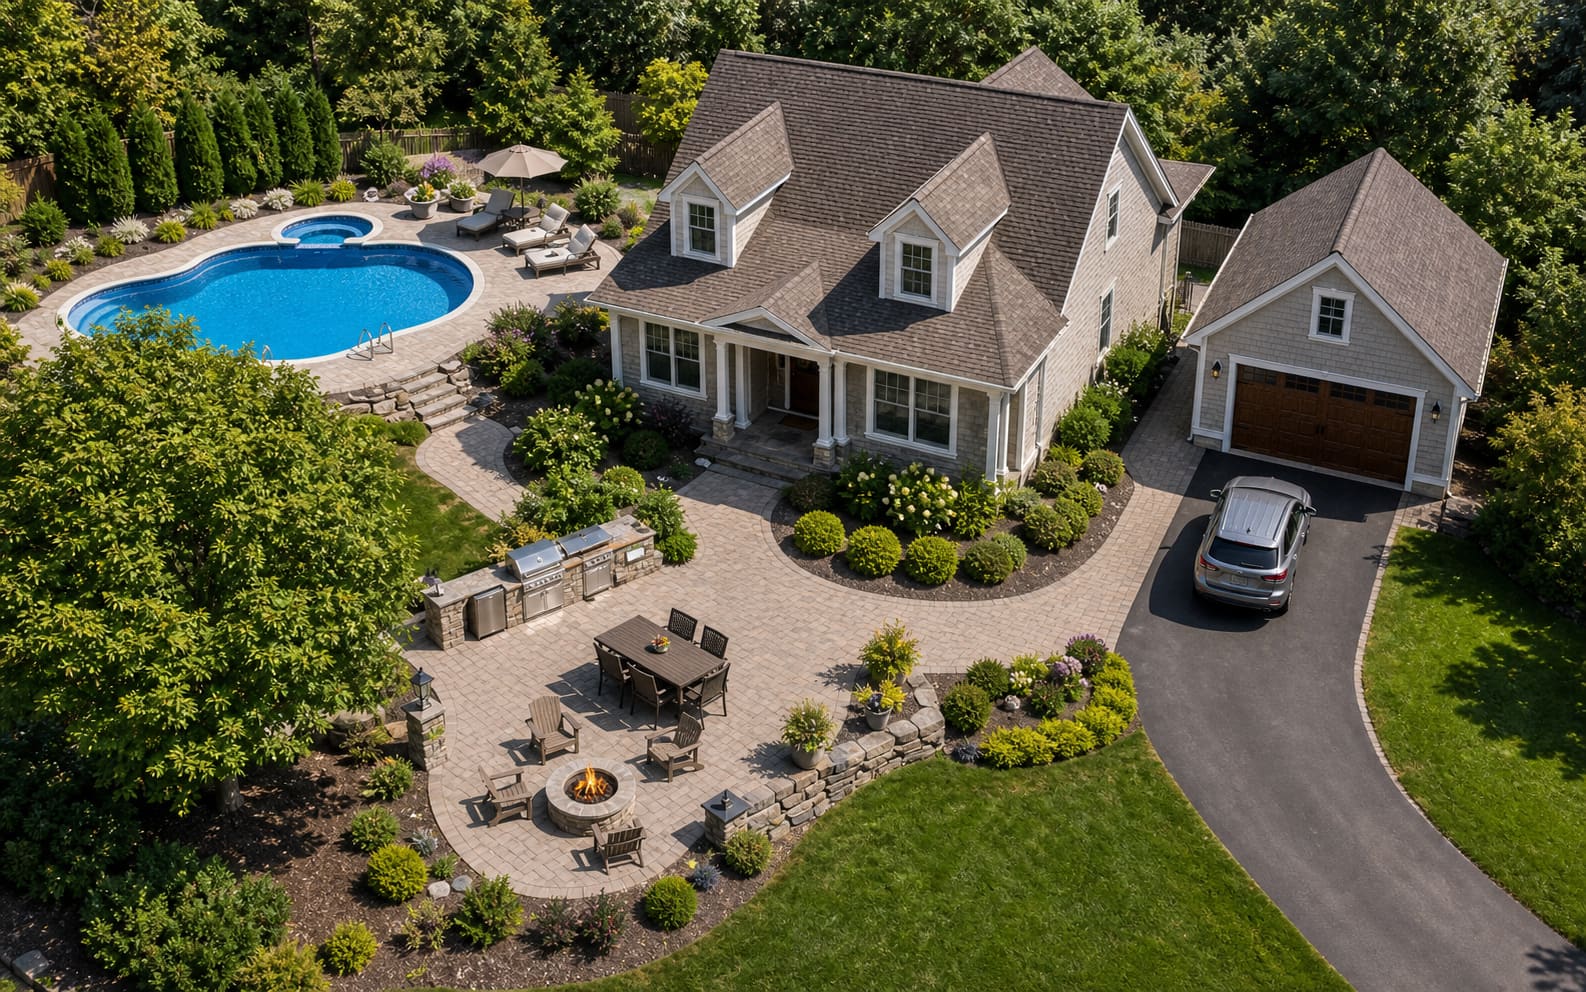
Explore common household risks and see how a homeowners policy may respond through dwelling, personal property, liability, and additional living expense coverage.
Coverage examples around the home
Coverage example
Risk Factor
How Coverage May Help
What makes Massachusetts different
Most home insurance advice online is written for the whole country. These are the things that specifically matter here, and the ones we end up explaining most often in the office.
Water and freezing are the dominant cause of loss
Short answer Non-flood water damage and freezing accounted for 36.4% of all Massachusetts home insurance losses by dollar value in 2024 — the largest single cause — at an average claim cost of $16,639. Wind and hail were a distant second at 9.2%.
The share moves with the weather — it was 46.5% in 2023 and 36.4% in 2024 — but water has been the top cause in both years, and the average claim has grown. Practically, that means the fine print on water damage matters more than almost anything else on your policy.
Sudden and accidental damage — a supply line that bursts in January — is typically covered. Gradual seepage, a slow leak that went unnoticed, and damage a carrier attributes to deferred maintenance are commonly excluded. Ice dam damage sits in between and is handled differently from one carrier to the next. That difference is invisible on a price comparison and very visible at claim time.
Flood is a separate policy, and almost nobody here has one
Standard homeowners policies exclude flood. So does the FAIR Plan. Coverage comes through the National Flood Insurance Program or a private flood carrier, and relatively few Massachusetts homes carry it.
In the Pioneer Valley that gap is worth taking seriously. The Connecticut River and its tributaries run through the middle of our service area, and flood risk does not stop neatly at the edge of a mapped flood zone. If you are near water, ask us to check your flood zone before you need to know.
Heating oil: coverage you are entitled to buy, and often don't have
This one catches people out. Under Massachusetts law — Chapter 453 of the Acts of 2008, as amended — owners of one- to four-unit homes heated with oil were required to have an oil safety valve or a sleeved supply line installed by a licensed technician. In return, insurers writing homeowners policies in Massachusetts must offer oil leak coverage to homeowners whose systems are certified compliant or exempt:
- At least $50,000 in first-party coverage for cleaning up a leak into soil, indoor air or other media at your home, plus personal property damage.
- At least $200,000 in third-party coverage where a leak has affected or is likely to affect groundwater or a neighboring property, including legal defense.
Buying it is optional, which is why so many oil-heated homes don't have it. The exposure is not small: a straightforward cleanup can reach $15,000, and a case involving groundwater can exceed $250,000. The upgrade itself typically ran $150–$350. If you heat with oil and have never been asked about this, call us and we will check whether your policy includes it.
The FAIR Plan is not a life sentence
The Massachusetts Property Insurance Underwriting Association — the FAIR Plan — is the state's insurer of last resort. It exists for homeowners who were declined, cancelled or non-renewed in the standard market, and it wrote 8.7% of Massachusetts home insurance premium in 2024. It has not filed a rate revision since 2013.
Two things are worth knowing if you are on it. First, it does not cover flood either. Second, and more usefully: being on the FAIR Plan does not count against you later. Voluntary carriers are not permitted to charge you more for having had FAIR Plan coverage. So if the reason you were placed there has since been resolved — the roof was replaced, a condition was repaired, an old claim has aged off — it may be possible to move you back into the standard market. We cannot promise that for any particular home, but it is a five-minute conversation and it is one of the more common ways we find people real savings.
On the FAIR Plan, or not sure why your rate is what it is?
A licensed agent will look at your situation and tell you honestly whether re-shopping is worth it.
What home insurance does not cover
Every policy has exclusions. These are the ones that surprise Massachusetts homeowners most often:
- Flood — separate NFIP or private flood policy.
- Earth movement — earthquake and sinkhole, usually an endorsement.
- Gradual leaks and seepage — the slow drip, as opposed to the burst.
- Maintenance and wear — an aging roof is not a covered loss.
- Mold — often capped tightly or excluded outright.
- Sewer and drain backup — commonly an add-on, not standard.
- Heating oil leaks — unless you added the coverage described above.
- High-value items above sub-limits — jewelry, art, firearms.
- Business activity at home — a home-based business usually needs its own policy.
Several of these are available as endorsements for modest money. The problem is almost never that they cannot be bought — it is that nobody raised them when the policy was written.
How Massachusetts homeowners lower the premium
| Lever | How it works |
|---|---|
| Multi-policy (home + auto) | The most commonly available discount, and usually the largest single one. |
| Claims-free history | Carriers weight recent claims heavily. One claim raises the average Massachusetts sample premium by roughly 14%. |
| Newer roof | Roof age is one of the strongest rating factors. A recent replacement can move a rate meaningfully. |
| Central or monitored alarm | Monitored fire and burglar systems are recognized by most carriers. |
| Automatic water shutoff device | Increasingly credited, and aimed squarely at the loss type that causes the largest share of Massachusetts losses. |
| Higher deductible | Lowers the premium, raises what you pay at claim time. Worth modeling both ways before you choose. |
| Paid in full / paperless / loyalty | Small individually, but they stack with the larger ones. |
| Oil system upgrade certification | Required to buy the oil leak coverage carriers must offer in Massachusetts — see above. |
Discount availability and amounts vary by carrier and by home, and are illustrative rather than guaranteed. Not every discount is offered by every carrier, and they do not all stack.
The lever most people never pull is simply re-shopping. Carriers change appetite and pricing constantly, and the carrier that was competitive on your home three years ago may not be today. We re-shop at renewal as a matter of course, because we are loyal to clients rather than to insurers.
Massachusetts home insurance FAQ
Is home insurance required by law in Massachusetts?
No. Massachusetts has no law requiring a homeowner to carry property insurance. If you have a mortgage, your lender almost certainly requires it as a condition of the loan, and they can buy a policy on your behalf and bill you for it if yours lapses. Once a mortgage is paid off, carrying coverage becomes your choice — though you are then absorbing the full rebuild cost yourself.
What does home insurance cost in Massachusetts?
Modeled sample rates put a Massachusetts home at about $2,075 a year with a $500,000 dwelling limit, and a Springfield home closer to $2,530 — roughly 22% above the state average. The Massachusetts Division of Insurance reported that average premiums rose again across homeowners, condominium and tenant forms in 2024, with statewide premium paid up 12.7% to about $3.9 billion. Your own premium depends on rebuild cost, roof age, claims history, deductible and carrier.
Does homeowners insurance cover flooding in Massachusetts?
No. Standard homeowners policies exclude flood, and so does the Massachusetts FAIR Plan. Flood coverage is a separate policy through the National Flood Insurance Program or a private flood carrier. Relatively few Massachusetts homes carry it, which means most homes near water are uninsured for flood damage. If you are near the Connecticut River or a tributary in the Pioneer Valley, this is worth a conversation.
Are ice dams and burst pipes covered?
Usually yes, when the damage is sudden and accidental — but the details decide the claim. Gradual seepage, long-term leaks and damage traced to a lack of maintenance are commonly excluded, and some policies treat ice dam damage differently from a burst supply line. Non-flood water damage and freezing was the largest single cause of Massachusetts home insurance losses in 2024 at 36.4% of total dollar losses, and the average claim cost $16,639 — so this is the exclusion language worth reading before winter rather than during a claim.
Does my policy cover a heating oil leak?
Only if you bought the coverage, and you can only buy it if your system is certified. Under Massachusetts law, insurers writing homeowners policies must offer oil leak coverage — at least $50,000 for first-party cleanup and $200,000 for third-party liability — to homeowners whose oil heating system has a compliant safety valve or sleeved supply line. The coverage is optional for you to purchase. A simple cleanup can run $15,000 and a groundwater contamination case can exceed $250,000, so the gap is significant if you heat with oil and never added it.
I'm on the Massachusetts FAIR Plan. Can I get off it?
Often, yes — it depends on why you were placed there. The FAIR Plan is the state's insurer of last resort for homeowners who were declined, cancelled or non-renewed in the standard market. It wrote 8.7% of Massachusetts home insurance premium in 2024, and it has not filed a rate revision since 2013. Being on it does not penalize you later: voluntary carriers are not permitted to charge you more for having had FAIR Plan coverage. If the original reason has been resolved — a roof replaced, a condition repaired, a claim aged off — it may be possible to place you back in the standard market. Call us and we will tell you honestly whether it is worth re-shopping.
Should I bundle home and auto?
Frequently it is the largest discount available to you, but not always the lowest total price. Bundling wins when one carrier is competitive on both lines. It loses when you are overpaying on one side to hold the discount on the other. Because we are independent and compare 20+ carriers, we can price it both ways and show you the actual difference rather than assuming the bundle is better.
Sources
- Massachusetts Division of Insurance, The 2024 Massachusetts Market for Home Insurance — cause-of-loss shares, average claim costs, catastrophe losses, premium growth and FAIR Plan market share.
- Commonwealth of Massachusetts, Homeowner Oil Heating System Upgrade and Insurance Law — the oil safety valve requirement and the coverage insurers must offer.
- Commonwealth of Massachusetts, Massachusetts Property Insurance Underwriting Association (FAIR Plan) — eligibility, what it covers, and leaving the plan.
- National Flood Insurance Program — flood coverage, which homeowners policies exclude.
- Sample rates by coverage level and city are drawn from NerdWallet's Massachusetts home insurance analysis (updated March 2026), using rates generated through Quadrant Information Services. These are modeled sample rates rather than quotes.
Keep reading
Costs and savings
- Bundling home and auto in Massachusetts: when it saves and when it doesn't
- Free policy review — what we look for
Massachusetts-specific
- Winter water damage: preventing the most expensive claim in Massachusetts
- When to update your dwelling coverage
- Coverage gaps Western Mass homeowners miss
Other policies you may need
- Condo insurance — what the master policy leaves to you
- Renters insurance
- Manufactured home insurance
- Umbrella insurance — extra liability above your home and auto limits
- Auto insurance in Massachusetts
- Jewelry insurance — for items above your policy's sub-limit
Serving Western Massachusetts
Springfield Chicopee Holyoke West Springfield Agawam Westfield Longmeadow East Longmeadow Ludlow Wilbraham all service areas